
Revolut gets UAE Central Bank licences: what local accounts mean for foreign property owners
The fintech has received regulatory licences and is preparing to offer banking services in the UAE, including multi-currency accounts and international transfers. For a non-resident who owns property in the Emirates, that is a practical matter rather than fintech news.
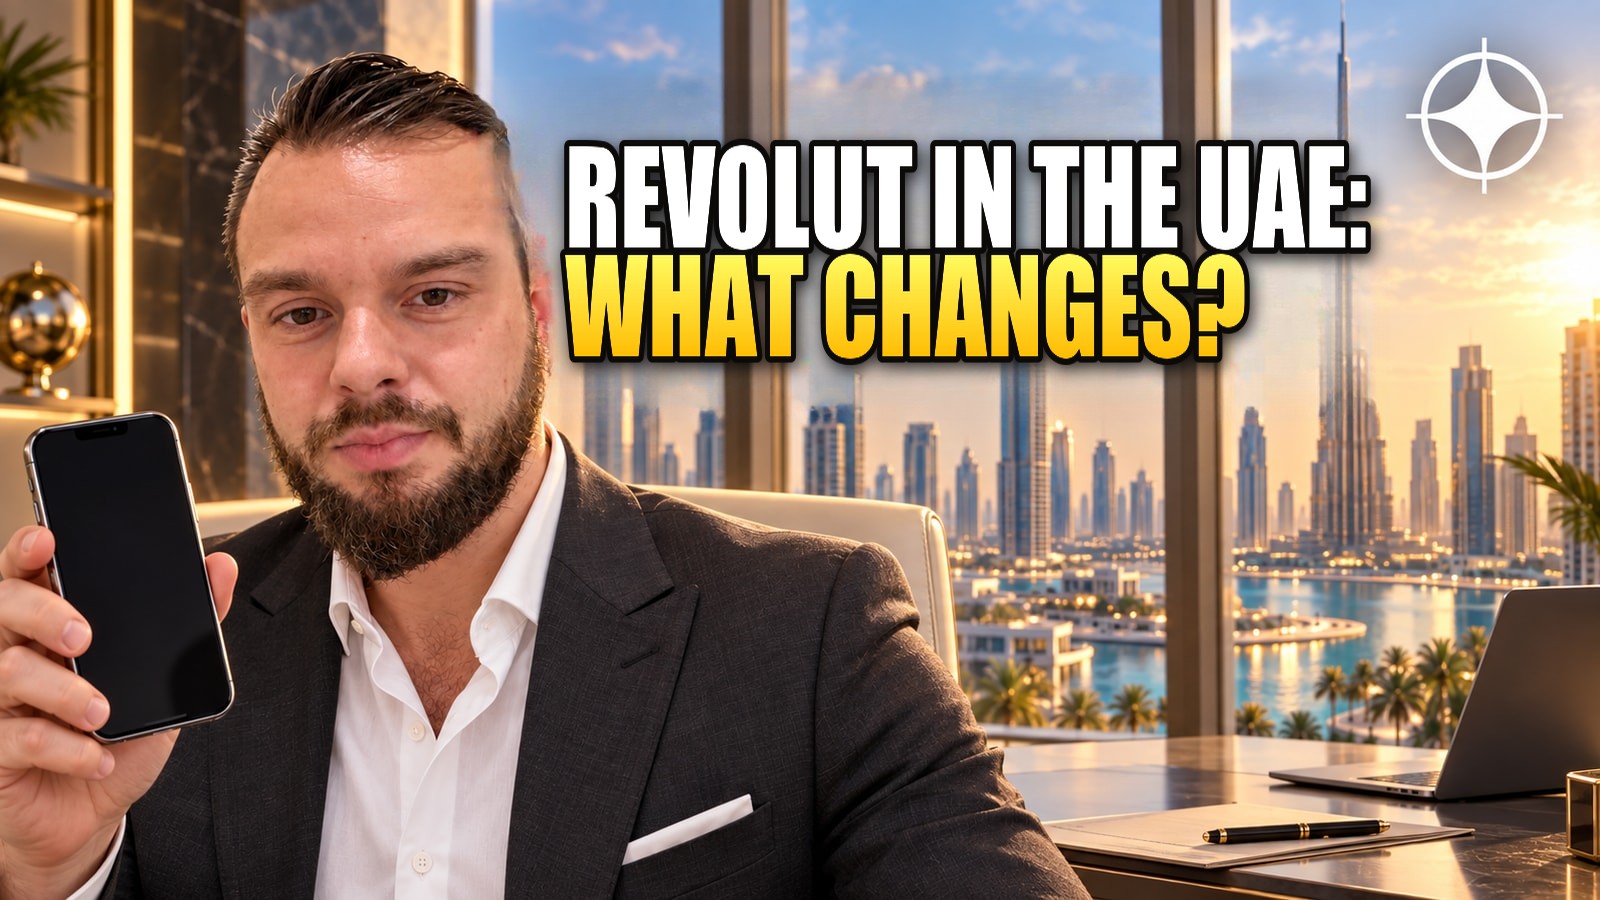
Revolut has received licences from the Central Bank of the UAE and is preparing to launch local banking services — multi-currency accounts and international transfers.
Why it matters to a property owner
The most underestimated difficulty of buying a home abroad is not the transaction itself but the payments around it. Paying the service charge, utilities and insurance, receiving rent, transferring income — all of it needs an account, and opening one at a local bank as a non-resident has traditionally taken time and required being there in person.
The arrival of a major fintech with a regulator's licence simplifies this part: a multi-currency account and transfers cover most of an owner's everyday tasks without a trip to a branch.
Talk to a licensed broker: 📲 +971 50 120 32 64 on WhatsApp, @dubai_oleg on Telegram
What it says about the market
A UAE Central Bank licence is neither quick nor given to everyone. A global player with a retail model entering the market is a sign that the regulator considers it mature enough for competition with traditional banks, and that the player itself sees a mass client base here.
For the property sector this is an indirect but durable signal: the infrastructure around owning an asset in the UAE is becoming more accessible, which lowers the barrier to entry for foreign buyers.
A caveat
Having a licence does not mean every service is available at once, or to every category of client. Terms for non-residents, transfer limits and compliance requirements should be checked when you open the account, not taken from the announcement.
Based on reports of Revolut receiving licences from the Central Bank of the UAE, 2026.
In the news
Other write-ups on the site about the same thing.
Revolut Secures UAE Central Bank Licences, Prepares Local Rollout
The fintech has secured licences from the regulator and is preparing to offer banking services in the UAE, including multi-currency accounts and international transfers. For a non-resident property owner, that’s a practical question, not just fintech news.
UAE Now Lets Tourists Open a Bank Account in Minutes
Since 30 April 2026, tourists can get an account and a digital card without a branch visit — built on the biometric profile created on entry, through a joint UAE Central Bank, ICP and ADCB service.
A mortgage in Dubai as a non-resident: deposit, rates and what the bank asks for
Non-residents borrow in the UAE, at a larger deposit and a higher rate than residents. What the loan-to-value caps are, which documents decide the answer, and why the valuation rather than the price sets the loan.
Crypto goes mainstream in the UAE: Dubai Duty Free payments and a Revolut licence step
Dubai Duty Free became the first Middle East retailer to accept cryptocurrency, and Revolut received in-principle approval for crypto services in the UAE. Crypto already pays for flights and property deals in the Emirates — what it means for real estate transactions.
A UK mortgage for a non-resident: who lends and on what terms
One of the most developed mortgage markets in the world looks different to a buyer with no British credit history and no sterling income. The difference starts with who will even look.
Moscow vs Dubai mortgages in 2026: the rate, the payment and the total cost
Market mortgage rates in Russia sit near 18.7% in September 2026; a non-resident in Dubai can borrow from 5%. On a comparable loan the total cost over 25 years differs several times over. We run the numbers and explain who can actually access the Dubai rate.