
EIBOR-3M back below 3.8% — what it means for Dubai mortgage holders
EIBOR-3M stood at 3.76% on 9 May 2026. Variable rates at the major banks have moved down; fixed rates have not. Who should be refinancing, and who should not.
EIBOR-3M stood at 3.76% on 9 May 2026. Variable rates at the major banks have moved down; fixed rates have not. Who should be refinancing, and who should not.
Video on this topic
The same subject on the English channel — each clip has a written version of its own.
 17:28Commercial mortgage in Dubai: offices, retail and warehouses under construction20 September 2026
 29:32Mortgage for the final payment in Dubai: how to finance the handover instalment17 September 2026
 10:40DIFC will vs mainland will in Dubai: costs, timelines and what each one covers19 September 2026

In the news
Other write-ups on the site about the same thing.
UAE Central Bank rate: from 5.40% to 3.65%, then the first hike to 3.90% — what it means for mortgages
Between September 2024 and December 2025 the UAE Central Bank cut its base rate six times, from 5.40% to 3.65%. On 17 September 2026 it followed the Fed with a 25 bp rise to 3.90%. On an AED 1.5m, 25-year loan that is about AED 210 a month.
A UAE mortgage for a non-resident: a 20% deposit, rates from 3.97%, and the arithmetic of leverage
The central bank cut its key rate from 5.4% to 4.9%, and banks were offering around 4% fixed for three years. With rental yields of 7–10%, borrowing starts working for the owner rather than against them.
Income needed for a mortgage in Dubai, and how the approval process works step by step
Salaried UAE residents typically need AED 15 000+ a month to clear most banks’ first screen; the self-employed face a higher bar; non-residents earning abroad face a separate, stricter set of terms. The one constant: total debt payments cannot exceed 50% of income.
Off-plan mortgage in Dubai: which banks and developers now lend before handover
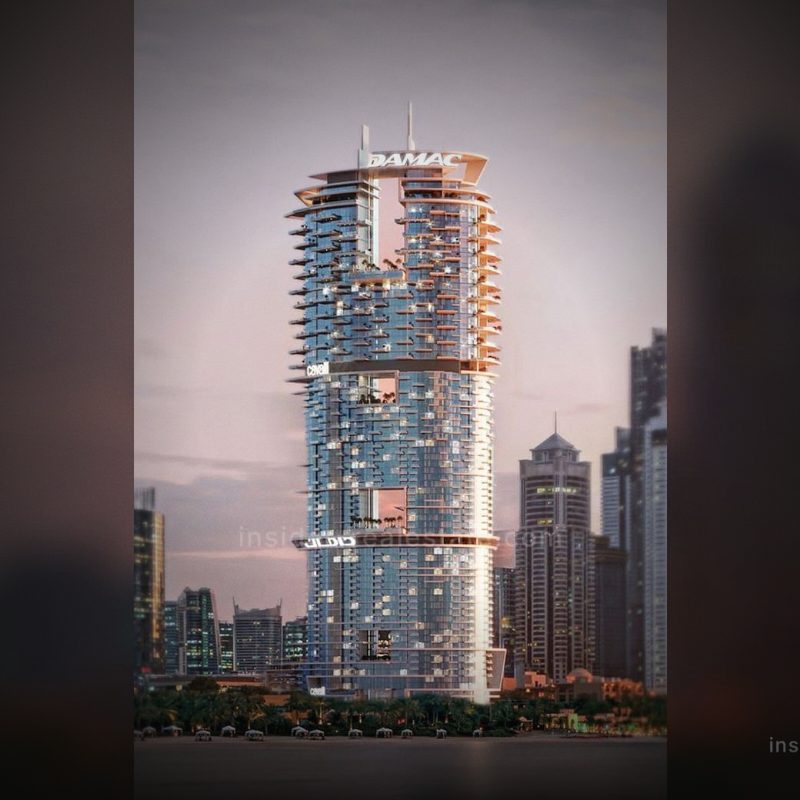
Damac and ADIB opened finance on projects 35% built once the buyer has paid 50% (March 2025). In 2026 Emirates NBD launched a scheme for Meraas, Nakheel and Dubai Properties from 30% completion, and ADCB a 12-month pre-approval from 3.49%.
Selling a mortgaged apartment in Dubai: payoff process, the early-settlement fee, and full costs
A UAE mortgage cannot transfer to a new property — selling always means paying it off in full, either with the seller’s own cash or the buyer’s funds at closing. Early settlement is capped at 1% of the balance or AED 10 000. Here is what a seller actually pays.
Islamic mortgage in the UAE: ijara, murabaha and musharaka explained for buyers
UAE banks offer conventional mortgages and Sharia-compliant financing side by side, open to any buyer regardless of faith. Ijara (lease-to-own) dominates residential deals; murabaha and diminishing musharaka show up less often. The Central Bank caps — 80% LTV, 50% DBR — apply to both.