Ready or off-plan in Dubai: the four differences that actually decide it
Not a matter of taste. When the money leaves you, when income starts, how a bank treats it and how you get out again are four different answers, and together they point at one option or the other for almost every buyer.
The ready-versus-off-plan argument is usually conducted as a matter of temperament — patient investor against cautious one. It is more useful as four concrete questions, because the answers are not a matter of opinion and they rarely point in different directions for the same buyer.
One: when the money leaves you
- Off-plan spreads the price across construction in instalments tied to milestones, and post-handover plans push part of it past the keys.
- The Land Department's 4% is paid up front, at registration of the preliminary contract — not at handover. The principal transaction cost therefore falls at the very beginning, when there is no property yet.
- Ready needs the whole sum at once, plus 7–8% on top for a cash purchase, of which the bulk is that same 4%.
- Agency commission differs. On a developer sale the developer pays the broker and the service is free to the buyer; on resale the buyer pays 2% plus VAT.
- A payment plan is worth real money, and it is worth exactly the cost of the capital you do not have to raise yet — which is why a slightly higher price on a longer, back-weighted plan can genuinely beat a lower price with most of it due before handover.
Two: when income starts
- A completed apartment lets from the first month, and in Dubai that means a year's rent in advance.
- Off-plan produces nothing until handover. The capital is exposed for the whole construction period and it is not working.
- The first letting season after a mass handover is the weakest. Several hundred near-identical units arriving in the same quarter means several hundred landlords competing in the same quarter. Model the second year, not the first.
- So off-plan is a capital-growth instrument and ready is a cash-flow one. Buying the first while needing the second is the most common mismatch on this market.
Three: how a bank sees it
- A mortgage on a completed property is an ordinary mortgage: valuation, loan-to-value cap, registration of the charge at 0.25% of the loan, arrangement fee, life and property cover. Budget roughly a further one and a half per cent on top of the cash transaction costs.
- Financing an off-plan purchase is a different conversation. It typically arrives at the end, to settle the final tranche, rather than at the beginning.
- Which means the decision belongs at the start of the plan. Discovering at handover that the final payment has to be financed, and on what terms, is the wrong moment to find out.
Four: how you get out
- Selling a completed apartment is an ordinary transfer at a trustee office, with a no-objection certificate from the developer and no permission required beyond it.
- Selling before handover is an assignment, it runs through the developer rather than between two owners, and without their consent it is not registered.
- There is a threshold in your contract — usually a share of the price paid, often around 30–40%, though both higher and lower occur — before an assignment is permitted at all.
- A strategy not supported by a clause in your own contract is not a strategy. Read the assignment terms before you need them.
And the difference that is not financial
With a completed apartment you inspect what you are buying: the corridors, the lifts, the parking, the state of the common areas, the service-charge history, the way the building has aged. With off-plan you are buying a specification and a track record, and the render is identical across the entire market. That is why the useful evidence in off-plan is what the developer has already delivered, how those buildings look five years on and whether handover dates held — and why in resale the useful evidence is the building itself.
The two risks, side by side
- Off-plan risk is delivery and timing: completing a year late, into a year when three neighbouring schemes also complete.
- Ready risk is the building: a weak owners association, a maintenance backlog, a service charge with a history, a specification that has not aged well. Two towers on the same street can differ completely, and none of it is visible from a floor plan.
- Both are researchable. Neither is priced into the listing.
Based on Land Department registration practice, central bank mortgage requirements and standard developer terms on this market.
Talk to a licensed broker: 📲 +971 50 120 32 64 on WhatsApp, @dubai_oleg on Telegram
Video on this topic
The same subject on the English channel — each clip has a written version of its own.
 29:32Mortgage for the final payment in Dubai: how to finance the handover instalment17 September 2026
 55:13Land plots and joint ventures in Dubai: how investors and developers split the profit9 October 2026
 10:22Australia vs Dubai property investment: 10/90 payment plans, tax and rental yield10 October 2026
 12:53Force majeure in Dubai real estate: can you withdraw from a deal?1 October 2026
 10:40DIFC will vs mainland will in Dubai: costs, timelines and what each one covers19 September 2026

In the news
Other write-ups on the site about the same thing.
Resale or rental in Dubai: two investor strategies compared, plus a third — flipping
Selling before handover returns 25% on capital if prices rise 10% and you have paid 40%. Renting pays 5.5–6.5% net every year. Flipping a villa: buy at AED 12.5m, spend 3m, sell from 19m. Three Dubai strategies compared on cash, time and risk.
Assignment six months before handover: the strategy that works when liquidity falls
A working scenario on a cooling market is buying an assignment at a high stage of completion. Four reasons it works, and the caveat about the premium.
Selling before handover in Dubai: why most off-plan resales do not happen
Assignment is the standard exit from an off-plan purchase, and it fails more often than it works. The three conditions that decide it, and why the developer’s permission is the smallest of the problems.
Mortgages for Resale Off-Plan Property in Dubai: An Exit From a Payment Plan You Can No Longer Afford
Dubai banks have started financing the purchase of under-construction units on the resale market. Conditions: building at least 50% complete, a limited developer list, and legal residency status. For an owner, it's a way to stay in the deal.
Dubai property investment mistakes: five errors that cost investors money, with the numbers
Five mistakes Dubai property investors repeat: trusting the 8% listing yield when the net is 6.7%, comparing prices instead of payment plans, buying the district not the building, entering with no exit plan, and believing a guaranteed 7%.
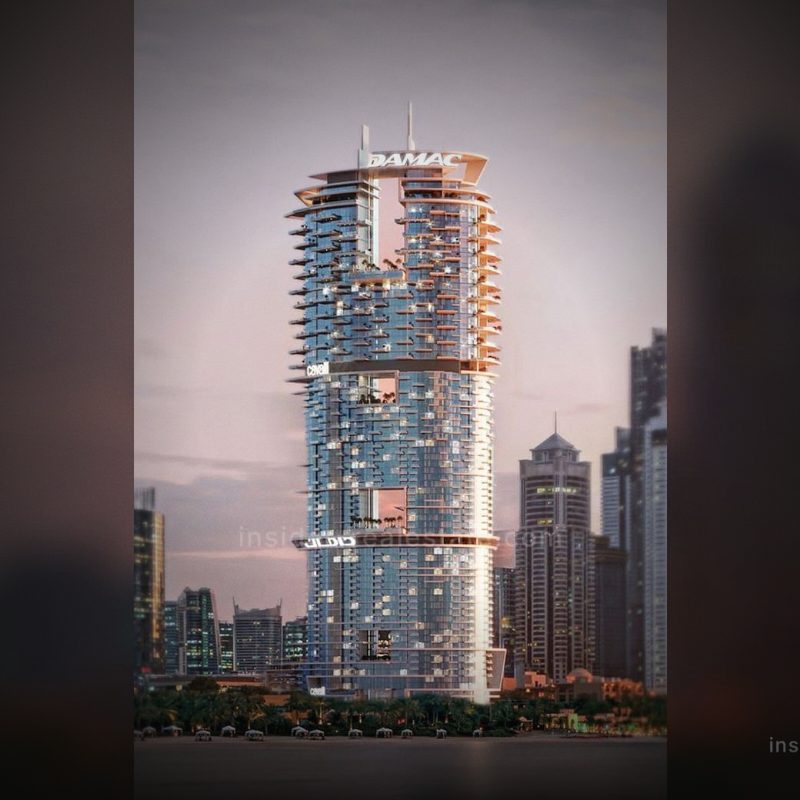
Off-plan mortgage in Dubai: which banks and developers now lend before handover
Damac and ADIB opened finance on projects 35% built once the buyer has paid 50% (March 2025). In 2026 Emirates NBD launched a scheme for Meraas, Nakheel and Dubai Properties from 30% completion, and ADCB a 12-month pre-approval from 3.49%.