
Using a mortgage broker in Dubai: what they do, step by step
A mortgage broker in Dubai matches a borrower to the bank whose lending policy fits them, prepares the file, negotiates the rate and stays with the deal through to registration. You can apply alone, in Dubai or Abu Dhabi, but banks differ enough that the match is where the saving is made, above all for a non-resident.
What does a mortgage broker actually do?
Four things. A broker selects the bank with the best terms for your situation, prepares the documents and so raises the chance of approval, negotiates the rate and conditions, and accompanies the transaction through to registration.
The value comes from the fact that banks offer different rates and requirements, and over a long term the difference can be substantial. A broker who knows the market matches the borrower to a suitable bank, which saves interest and shortens the process.
Mortgages are available to residents and non-residents in both Dubai and Abu Dhabi, but the conditions and the list of banks differ between the two emirates. Knowing the specifics of each market is part of what a broker is for.
Talk to a licensed broker: WhatsApp +971 50 120 32 64 · Telegram
What are the steps from pre-approval to registration?
There are five. Pre-approval, which gives a preliminary decision and a limit. Choosing a property within that budget. The bank’s valuation of it. Signing the mortgage contract and the sale and purchase agreement. Registration of the transaction at the Land Department.
The order matters. The typical borrower’s mistakes are to go shopping without pre-approval, to underestimate a floating rate, and to overlook the accompanying costs such as insurance and fees.
A broker’s contribution at this stage is unglamorous and useful: keeping the sequence intact, steering round those traps, and calculating the real monthly load before anything is signed.
What do banks really look at in a non-resident?
Document lists look alike from bank to bank, but a few factors decide the outcome. The first is stable, provable income: an official salary arriving regularly in an account reads better than an entrepreneur’s higher but irregular earnings.
The second is debt load. Existing loans and credit card limits reduce the amount available, because the bank calculates a combined ratio of payments to income.
The third is the country and currency of income: earnings in a stable currency from a jurisdiction with a transparent banking system make underwriting simpler. The fourth is age — the term is capped by a maximum age at final repayment, so an older borrower gets a shorter term and a higher monthly payment.
A non-resident should expect more conservative terms than a resident: a lower loan-to-value ratio, stricter proof of income and a shorter list of banks. It is not a closed door but a different corridor of parameters, and it is where access to several lenders helps most.
Understanding these mechanics before applying saves weeks, because the file goes straight to the banks whose credit policy is compatible with your profile.
What does the whole transaction cost?
More than the rate suggests. A set of one-off costs is paid in cash and is not covered by the loan: fees for registering the transfer of title, mortgage registration, the valuation, the bank’s arrangement fee, life and property insurance, and the agent’s commission on a resale purchase.
The down payment comes from your own funds, and its size depends on the borrower’s status and the value of the property. Transaction fees together make a noticeable addition to the price, so plan them as a separate line, not out of whatever is left.
Insurance is an annual payment for the whole term of the loan. Policies from different providers differ in price and can be compared. Keep a reserve too — a cushion of several monthly payments in case of a change of job or a delay in rental income.
Ask separately how the rate is structured. Many products fix the percentage for the first years and then move the loan to a floating rate tied to a base indicator. Model the payment if that indicator rises: a comfortable sum today must not become a critical one tomorrow.
Does a mortgage work the same way for off-plan?
No. A classic mortgage works with completed property: the bank values a specific flat, registers the charge and finances the purchase from the seller. With property under construction, some banks lend only on projects by accredited developers, and usually at late stages of completion.
Until then the buyer pays instalments under the developer’s schedule from their own funds. If the plan is to settle the balance with a loan at handover, agree it with a broker in advance, several months before the final payment.
Pre-approval shows the amount genuinely available, and knowing which banks work with your developer removes the main risk — reaching the final instalment with no financing in place.
On the resale market pre-approval is just as valuable. Sellers take a buyer with a confirmed limit more seriously, and the transaction moves faster.
When is refinancing worth it?
When market rates have fallen relative to yours, or when the fixed period has ended and the loan has moved to an unfavourable floating rate. A mortgage in the UAE does not tie you to the original terms for life, and moving to another bank can cut the payment noticeably.
The sum has to be done honestly: the gain from the new rate against the cost of moving — early repayment charges, and new fees for arrangement and registration.
As a rule refinancing makes sense when the difference in rate is noticeable and the remaining term is long enough for the saving to cover the cost of switching. A broker is as useful here as at the first loan: they see the banks’ current offers and can calculate the break-even point.
A sensible habit for the owner of a mortgaged property is to compare their rate with the market once a year. It takes a single enquiry, and it can save money for years.
Frequently asked
Do I need a broker to get a mortgage in Dubai?
No, you can apply to a bank yourself. A broker is useful because banks differ in rates and requirements: matching the borrower to a suitable bank saves interest and time, and the help is most valuable to a non-resident.
Can a non-resident get a mortgage in Dubai or Abu Dhabi?
Yes, in both emirates, though on more conservative terms than a resident: a lower loan-to-value ratio, stricter proof of income and a shorter list of banks. Conditions and the banks available differ between Dubai and Abu Dhabi.
Which costs of a Dubai property purchase are not covered by the mortgage?
The down payment and the one-off costs: title transfer and mortgage registration fees, the valuation, the bank’s arrangement fee, life and property insurance, and the agent’s commission on a resale purchase. They are paid in cash and should be budgeted as a separate line.
Can I use a mortgage to pay for an off-plan property?
Partly. Some banks lend only on projects by accredited developers and usually at late stages of completion; before that, instalments are paid from your own funds. To finance the final payment at handover, start with a broker several months ahead.
✍️ Message me on WhatsApp for a free consultation — off-market stock, payment plans and honest numbers on any of the projects covered here.
✅ Subscribe on YouTube — investment, property, business and relocation in the UAE and beyond.


In the news
The same subject in writing — analysis and news related to this video.
Ready or off-plan in Dubai: the four differences that actually decide it
Not a matter of taste. When the money leaves you, when income starts, how a bank treats it and how you get out again are four different answers, and together they point at one option or the other for almost every buyer.
Mortgages for Resale Off-Plan Property in Dubai: An Exit From a Payment Plan You Can No Longer Afford
Dubai banks have started financing the purchase of under-construction units on the resale market. Conditions: building at least 50% complete, a limited developer list, and legal residency status. For an owner, it's a way to stay in the deal.
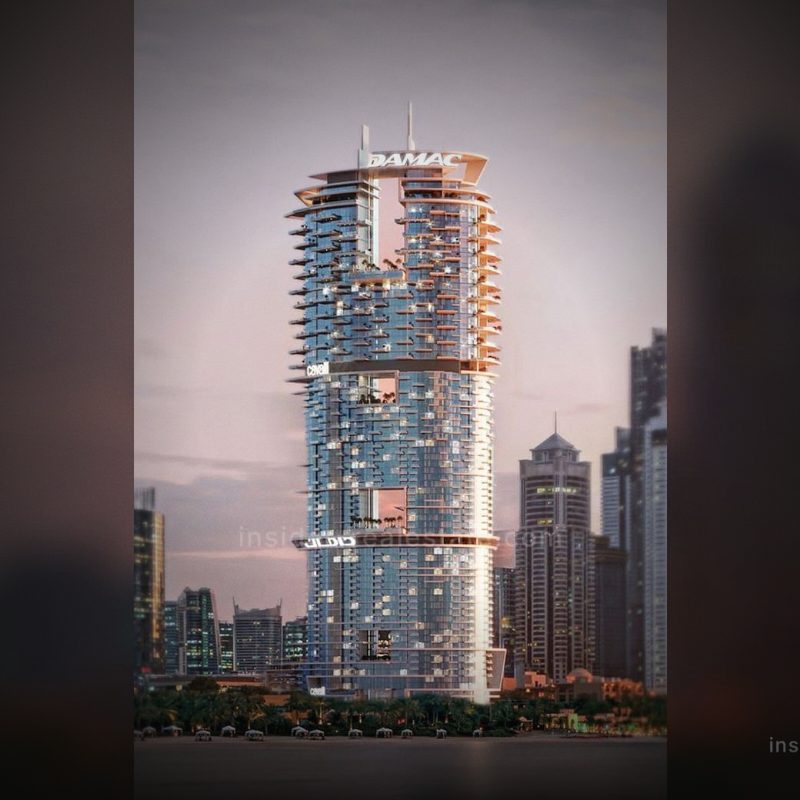
Off-plan mortgage in Dubai: which banks and developers now lend before handover
Damac and ADIB opened finance on projects 35% built once the buyer has paid 50% (March 2025). In 2026 Emirates NBD launched a scheme for Meraas, Nakheel and Dubai Properties from 30% completion, and ADCB a 12-month pre-approval from 3.49%.
UAE Golden Visa through property in 2026: mortgages, off-plan and how Dubai, Abu Dhabi and RAK differ
The threshold is AED 2m everywhere, but it is not measured the same way. Since January 2024 Dubai counts a mortgaged home at its full DLD valuation; Abu Dhabi wants AED 2m of your own equity. Mortgages, off-plan, three emirates and what the visa gives beyond residence.
Off-plan mortgages arrive in Abu Dhabi: 75% financed from the start of construction
A product the off-plan market did not have: bank financing that accompanies the buyer from the start of construction through to handover. How it works, and why it closes the segment’s structural problem.
Moscow vs Dubai mortgages in 2026: the rate, the payment and the total cost
Market mortgage rates in Russia sit near 18.7% in September 2026; a non-resident in Dubai can borrow from 5%. On a comparable loan the total cost over 25 years differs several times over. We run the numbers and explain who can actually access the Dubai rate.