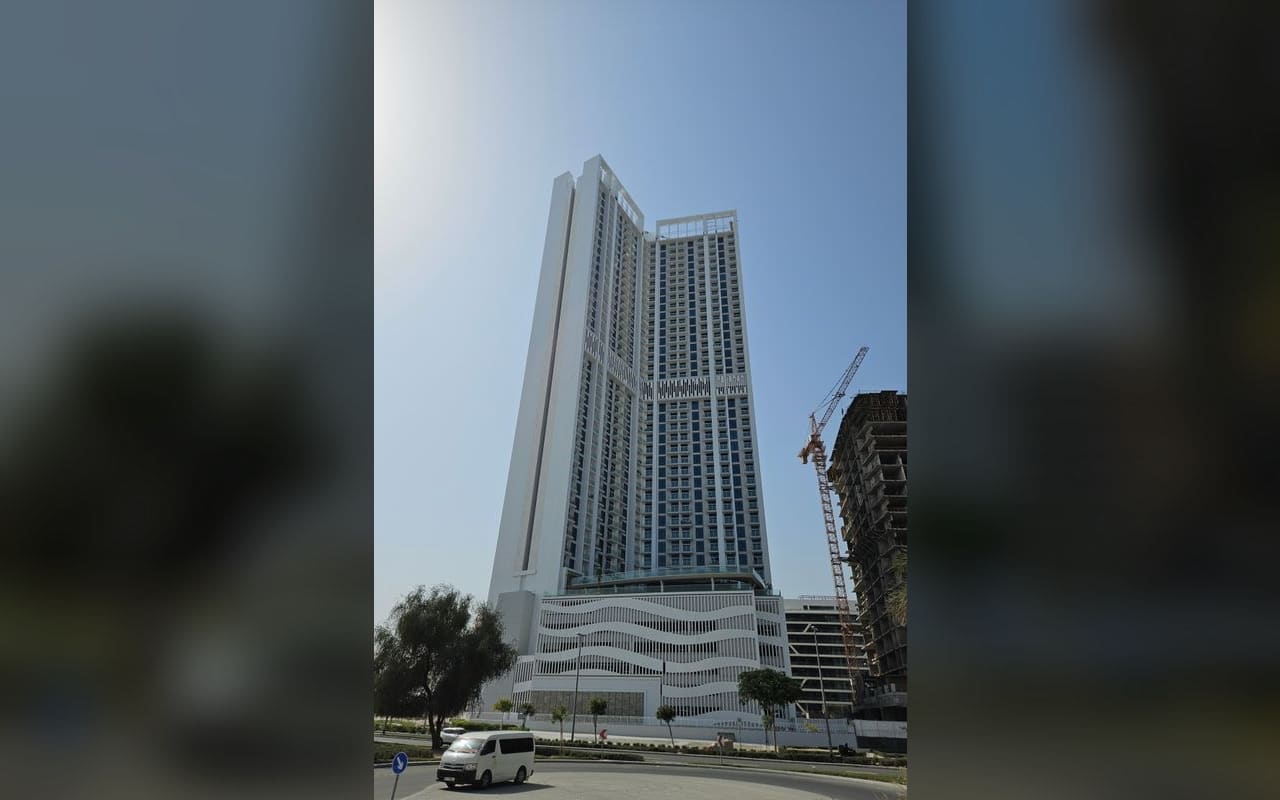
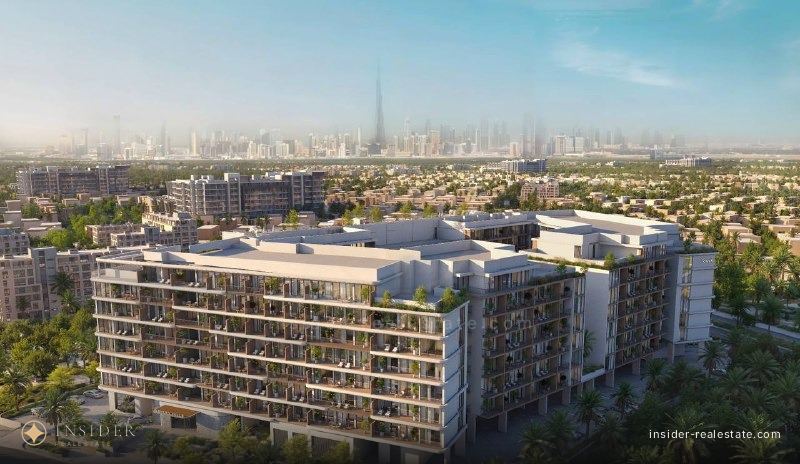
Binghatti Hills at Arjan: the volume play, examined
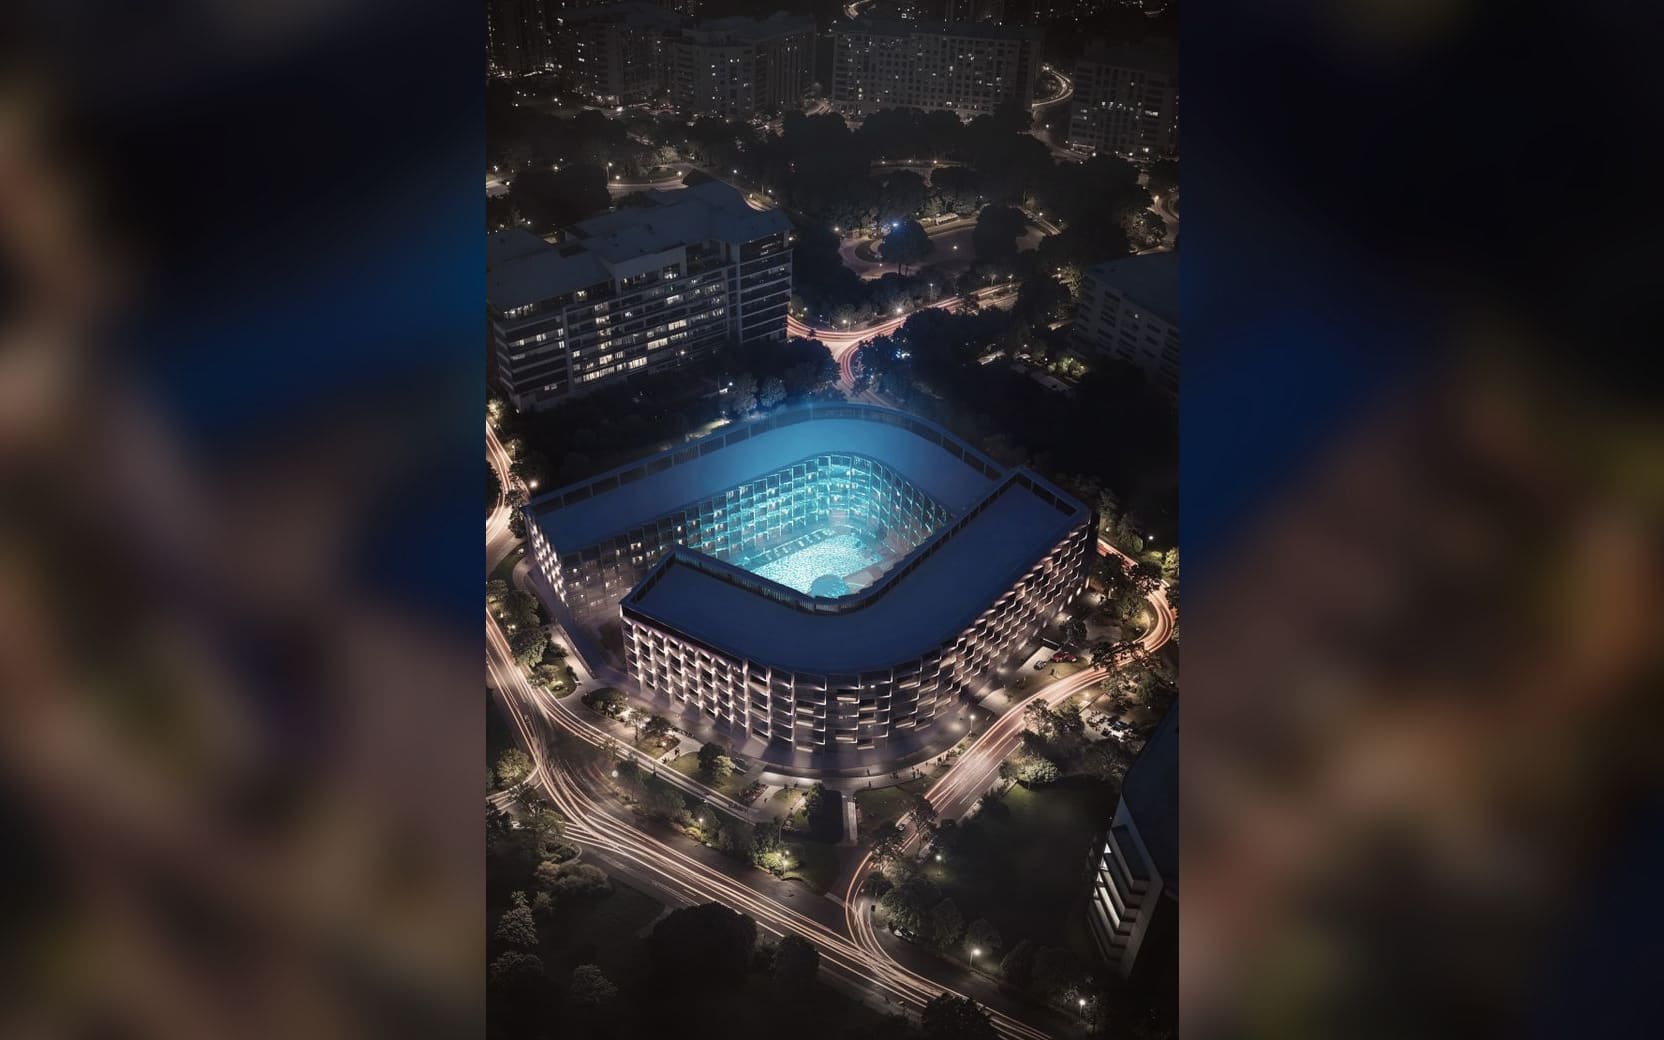
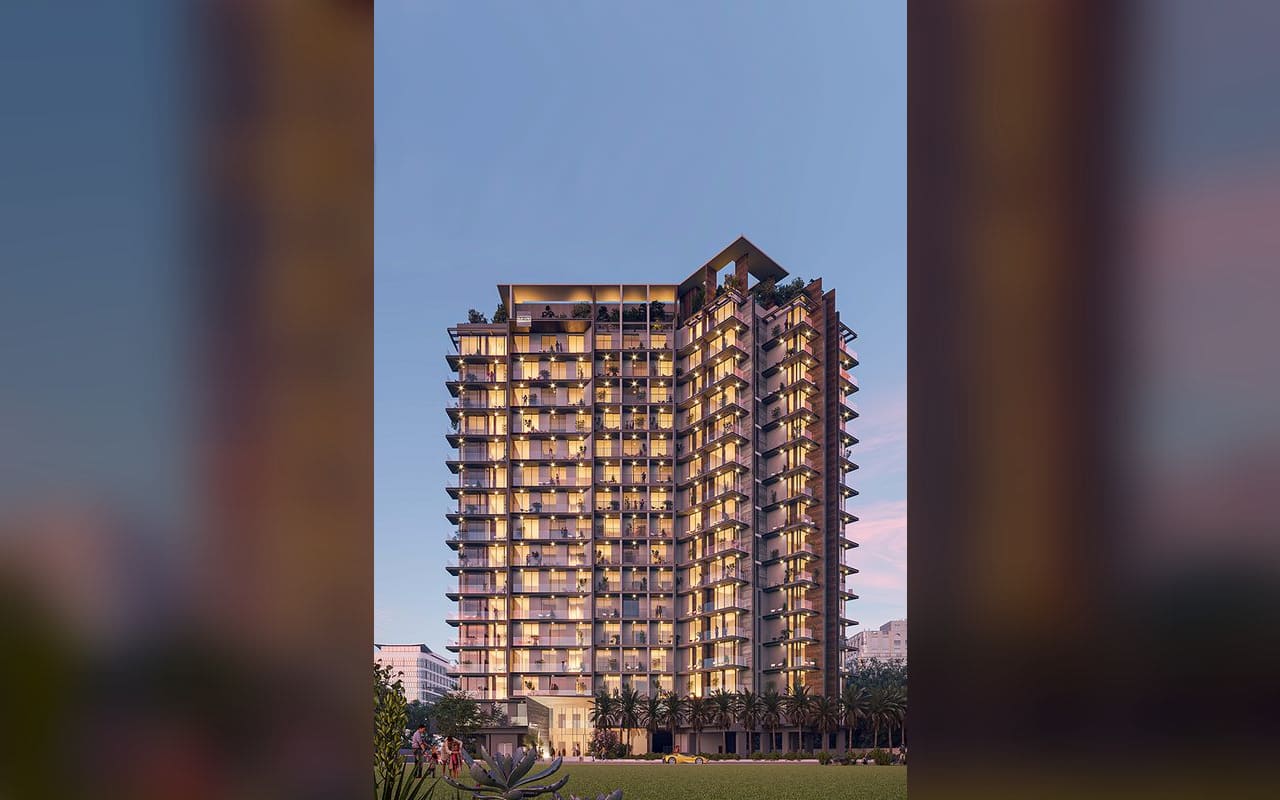
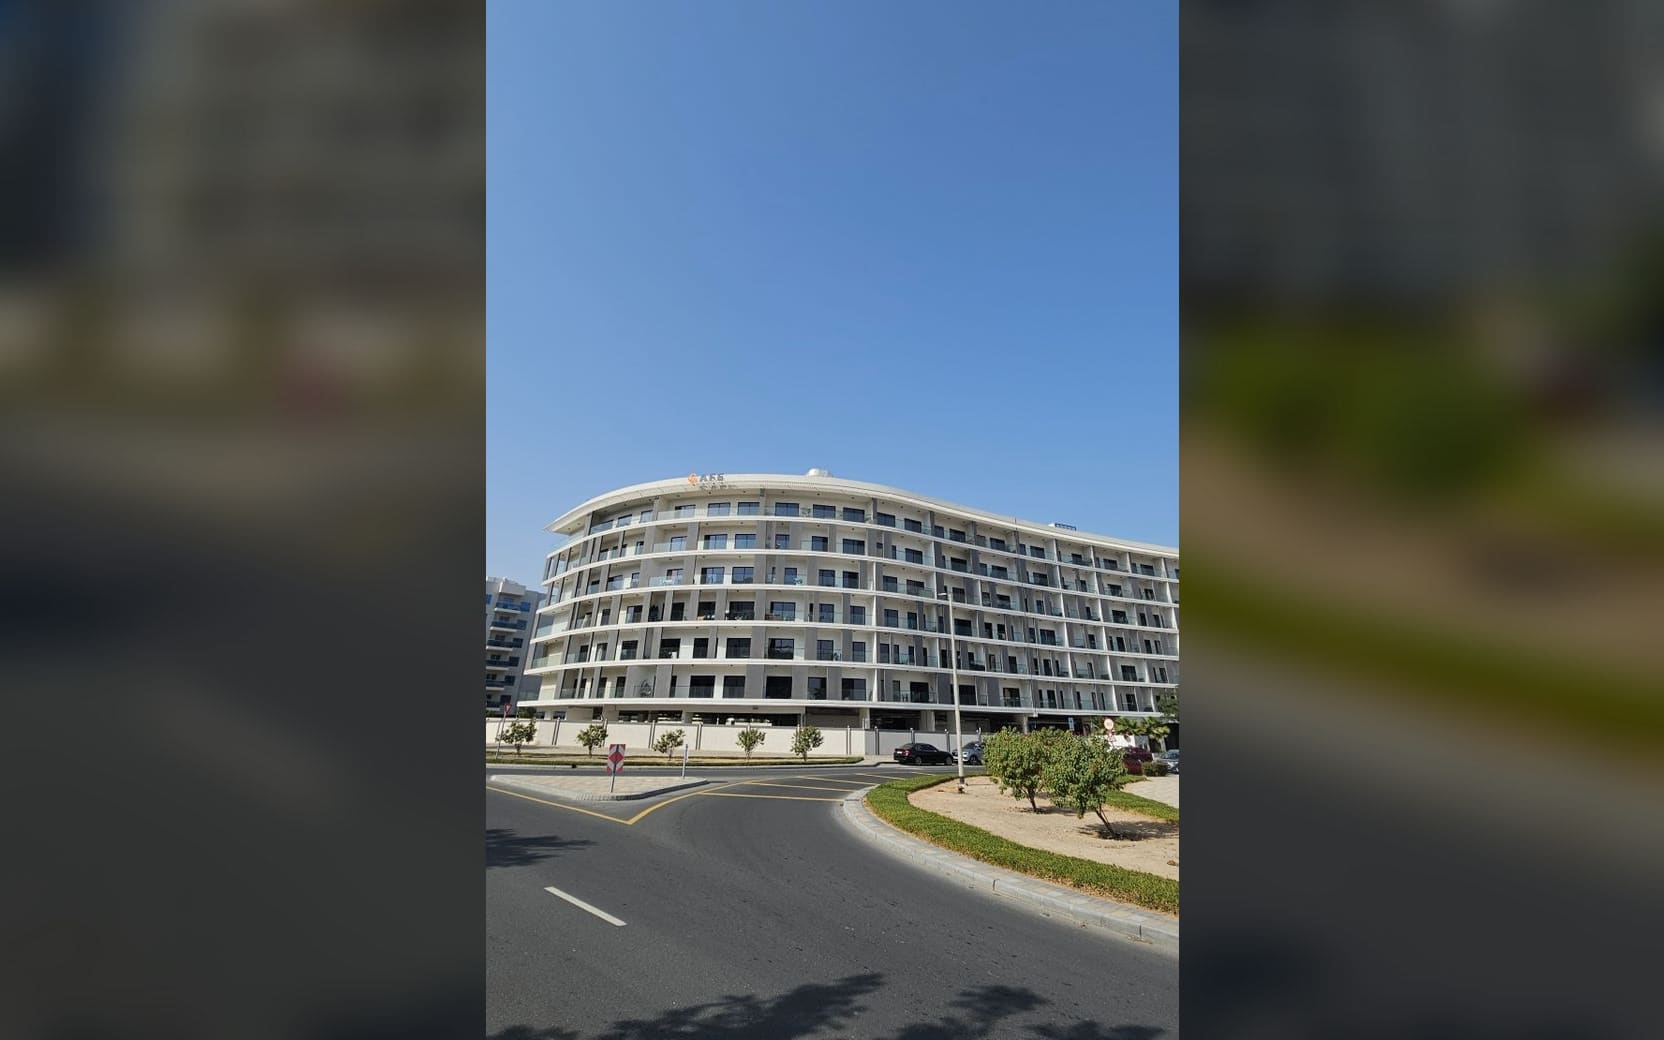
Binghatti Hills is one of the largest residential projects in Arjan. What buying into a very large mid-market development actually means for rent, resale and service charge.
10 September 2025
 INSIDERrealestate — Home
Rates are indicative. Contracts and DLD fees are always in dirhams.
A dense apartment district beside Dubai Science Park, best known to visitors for Miracle Garden and to investors for its yields.
33 units in stock. 22 with a confirmed status: 7 ready, 15 under construction. 87th most expensive of 91 districts by median price.
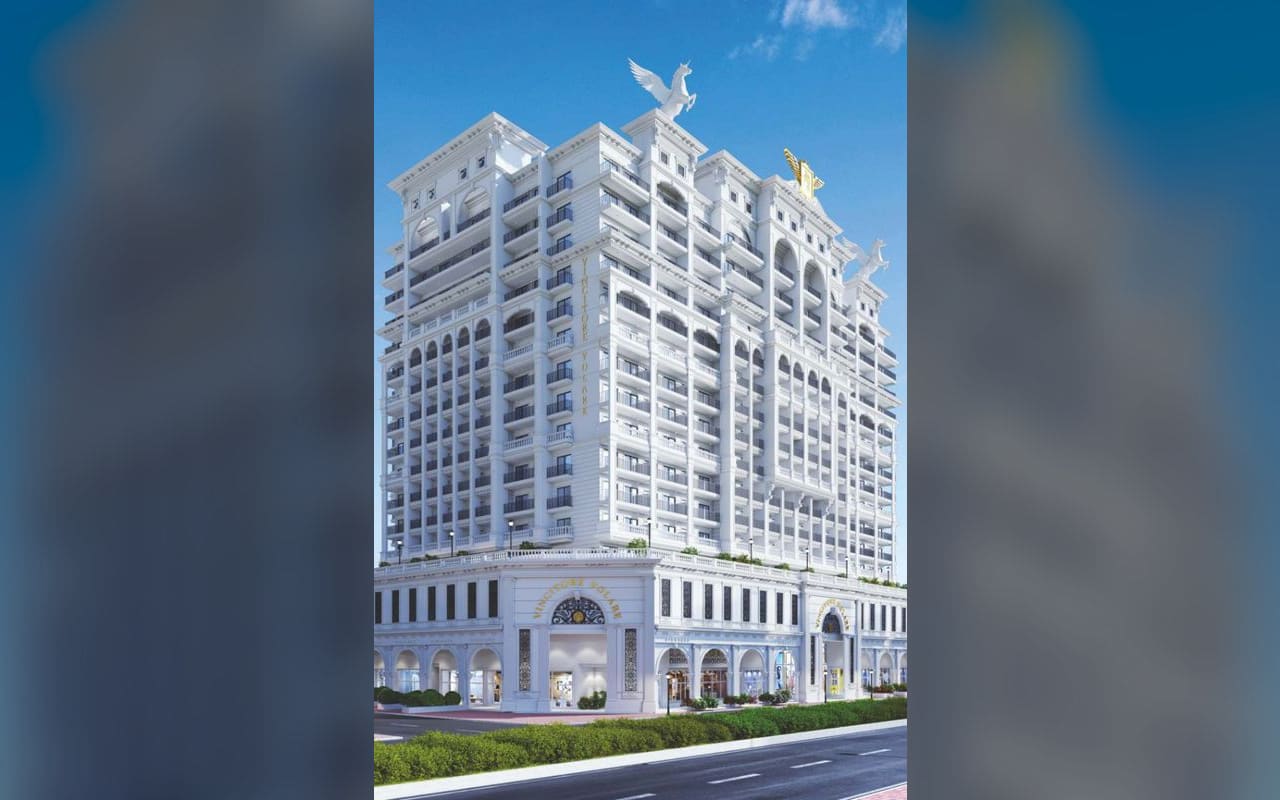
Arjan is a mid-density residential district in the Dubailand region, bordered by Dubai Science Park and Al Barsha South, built almost entirely of apartment buildings rather than houses.
It filled in rapidly through the late 2010s and 2020s and continues to add supply, with a wide range of developers building independently on separate plots.
It contains Dubai Miracle Garden and the Butterfly Garden, which bring substantial seasonal visitor traffic and no residential benefit whatsoever.
Employees at Dubai Science Park and the surrounding business parks, families priced out of Al Barsha and Dubai Hills, and a large population of couples and sharers who want newer buildings than the older mid-market stock offers.
It is a price-sensitive tenant pool by definition — they chose Arjan because it was cheaper — which means a comparable building two streets away dropping its rent will move them.
Tenancy lengths are moderate and churn is higher than in the family districts.
Arjan competes on entry price. Rents per square foot are lower than in central districts but purchase prices are much lower, and the ratio has generally been favourable — gross yields here run above the Dubai average.
That is the whole investment argument, and it is a legitimate one. What it is not is a capital growth argument: land is available, supply responds, and prices stay anchored.
Newer buildings let faster and command a premium over the earlier stock, which is worth factoring into a purchase decision.
No metro and none planned, so the district is entirely car-dependent and parking allocation is a real determinant of rent.
Traffic around Miracle Garden during the winter season is genuinely disruptive, with visitor coaches and cars on the surrounding roads.
Amenity is functional: supermarkets, clinics, nurseries and a growing number of restaurants, but no district centre. Residents drive to Mall of the Emirates, Dubai Hills Mall or Cityland.
Schools are in the surrounding areas rather than inside the district.
The building and its developer, since Arjan has the same independent-plot problem as JVC and the same quality variance.
Distance from the Miracle Garden traffic corridors if you or your tenant will be driving in the winter season.
Parking allocation, particularly on studios.
The service charge relative to the achievable rent, which in a lower-rent district consumes a larger share of gross income than the absolute figure suggests.
Handover schedules for adjacent plots, because a mass handover next door softens rents for a season.
A yield-focused investor with a long horizon who wants a low entry price and accepts a mid-market finish and minimal capital appreciation.
A buyer who wants to own Dubai property at a ticket size that does not require financing.
It suits poorly anyone hoping to flip in a district with thousands of competing units, and anyone who needs a distinctive asset.
Arjan borders Dubai Science Park, a free zone for life sciences, pharmaceuticals, healthcare and environmental businesses. It is not large by Dubai standards, but it is a genuine employment cluster with laboratories, offices and company headquarters rather than an empty business park.
That anchor is what separates Arjan from a purely speculative district. There are people who need to live within a short drive of a specific building, and they are professional, reasonably paid and inclined to stay.
Al Barsha South and Dubai Hills next door extend the pool further, adding healthcare staff, teachers from the school cluster and households priced out of Dubai Hills itself.
Underwrite that pool rather than the district’s marketing. It is real, it is stable, and it is also finite — which is why rent growth here has been modest even as the population grew.
From roughly November to May, Dubai Miracle Garden and the adjacent Butterfly Garden draw very large visitor numbers, and the traffic arrives by coach and by car on the roads that Arjan residents use.
The effect is concentrated: buildings on the main approach corridors experience it daily through the season, buildings a few streets away barely notice. It is worth establishing which side of that line a property sits on.
There is no residential benefit whatsoever — the gardens are ticketed tourist attractions, not community amenity, and residents do not use them.
On the positive side, the attractions have brought a cluster of cafés and restaurants to the area that would not otherwise exist at this price point, and they operate year-round.
Arjan has the same independent-plot development pattern as JVC and the same consequence: the district average conceals a very wide range. Two towers on the same street can differ substantially in layout efficiency, parking provision, lift performance and management.
Prefer newer stock from a developer with delivered buildings you can inspect. In a district where every unit competes on price, the newer building lets first and holds its tenant longer.
Confirm the parking bay. Arjan has no metro and no realistic prospect of one, and a unit without a bay lets at a discount to a unit with one.
Check the handover schedule for neighbouring plots before modelling your first year. A mass handover next door softens rents for a full letting season, and Arjan has had several.
Prices, developers and the things that go wrong — walkthroughs from the channel.
The index covers the emirate as a whole; the Land Department publishes no separate figure for Arjan. Read it as backdrop — is the market rising or flat — against the prices above. Deals in a particular Arjan building I can pull separately if you ask. Source: Dubai Land Department, read 15/08/2026.
The quarterly Land Department index is one number for the whole emirate. The monthly one counts villas and apartments separately — and in 2026 that is the point, because a blended average masks how far the segments have diverged.
By completion status the month broke down as 72.8% off-plan and 27.2% ready. Ready-home deals grew 11.4% month on month; off-plan was the one segment lower against both the previous month and the previous year (−45.3%). In practice: apartments and off-plan leave room to bargain, finished villas in settled communities far less. Index base is January 2021 = 100 — a villa reading of 292.5 means growth of 192.5% from that mark, not a premium over a 2021 peak. Monthly ValuStrat market review for July 2026, checked 24/08/2026.
It offers above-average gross yields at low entry prices with a stable tenant base from Dubai Science Park and nearby business districts. The constraints are no metro, a price-sensitive tenant pool and continuing new supply that caps appreciation.
During the winter season it generates substantial visitor traffic on the surrounding roads, including coaches. Buildings away from the main approach corridors are noticeably less affected.
RTA fully opened phase one of the Hessa Street upgrade in April 2026: 4.5km, four lanes each way, capacity up from 8,000 to 16,000 vehicles an hour, and the Sheikh Zayed Road–Al Khail Road run cut from 15 minutes to about 4.
A developer building in Arjan and Discovery Gardens. In districts with large amounts of old, cheap rental stock, your new building competes with it — and that sets a ceiling.
A developer that built a large pipeline quickly in Arjan and the growth clusters. What to verify when the pipeline is bigger than the delivery record.
A developer competing on decoration in Arjan and the mid-market districts. Where a distinctive facade genuinely helps, where it does not, and what to check underneath it.
Transaction statistics on Dubai retail units give an unexpected picture: activity leads not at prestige addresses but in mass residential districts.
Tell me which building or unit it is. Before you make an offer I will bring the registered transaction history, the current service charge and the real letting prices of comparable units.
Ask on WhatsAppTelegram is the fastest way — I answer personally.
Message on Telegram